Virtual Land vs VR Collectibles: Where Digital Ownership Actually Lives in 2025
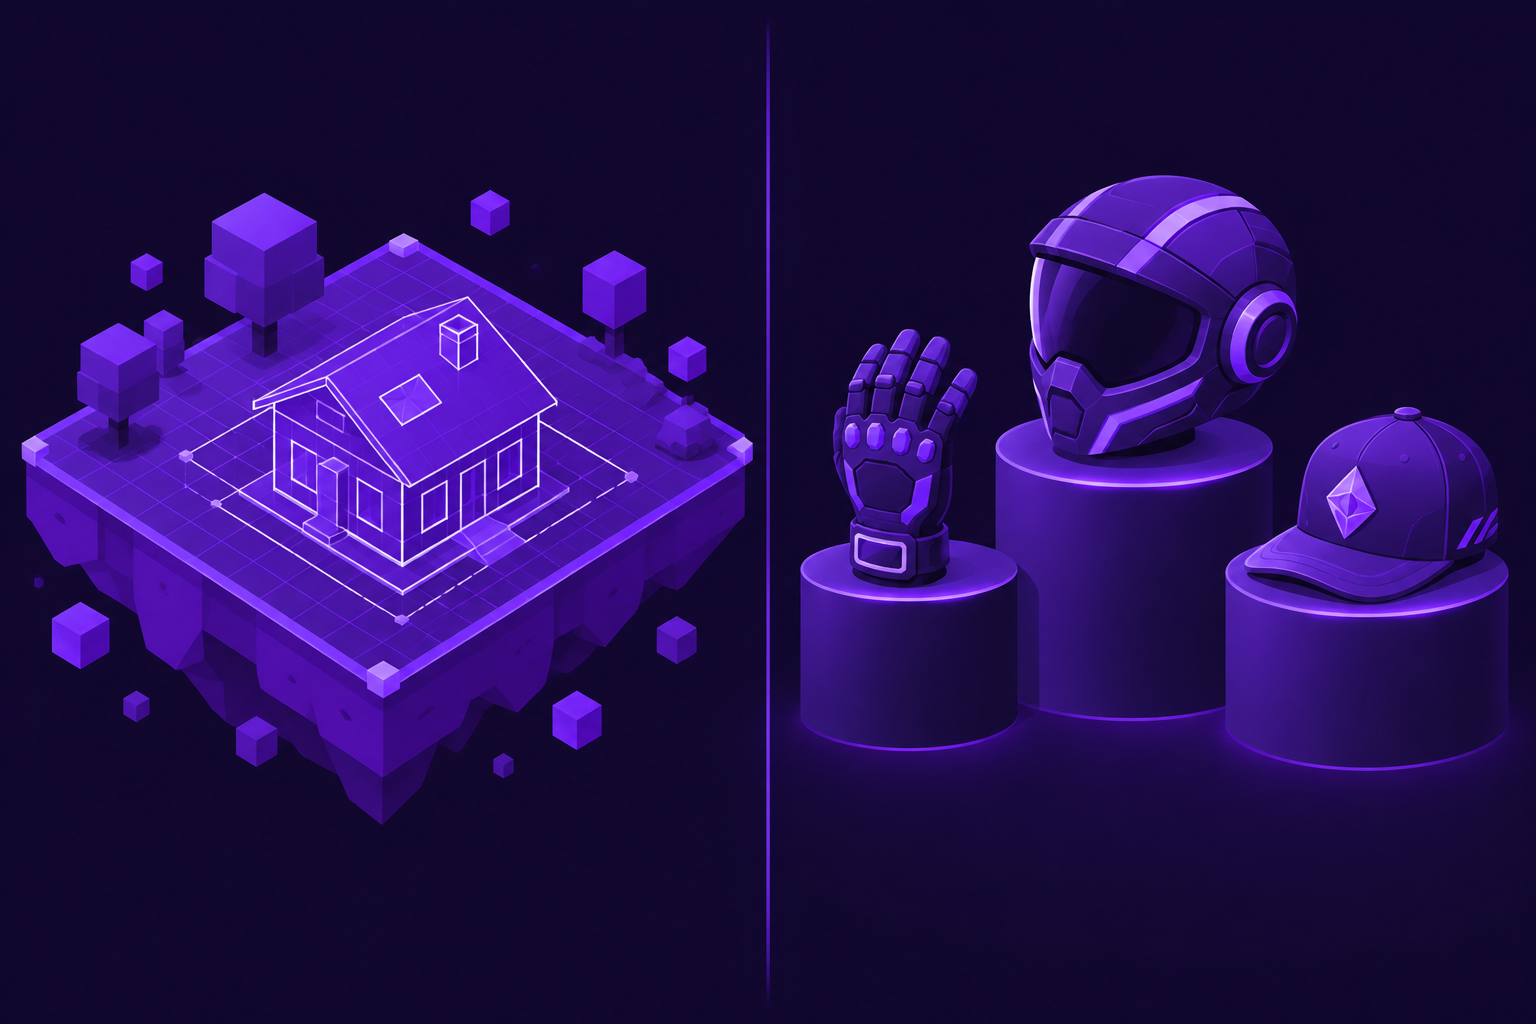
“VR NFTs” conflates two different asset classes that behave very differently: virtual-world land/items (Sandbox LAND, Decentraland parcels, Otherside deeds) and VR-native collectibles (avatar wearables, 3D assets, in-world items). Knowing which you’re looking at is the first filter for any collector.
Virtual land: the survivors consolidate
Decentraland and The Sandbox remain the two canonical land platforms — both operational, both quieter than 2021. Decentraland still runs events (Metaverse Fashion Week, April 2025) and is mid-engine-upgrade; The Sandbox held its largest LAND auction in July 2025. Land now trades on utility — what you can build, host or rent — rather than location speculation.
Otherside: the newest entrant’s approach
Yuga Labs’ Otherside took a different path: persistent-world tech first, land speculation second. Its August 2025 release of AI-powered world-building tools signals the platform’s bet that creators, not landowners, drive value.
VR-native collectibles
Wearables, avatar items and 3D assets trade across both platforms and external marketplaces. Their value tracks the platform they’re usable in — a wearable for a world with 8,000 daily users carries a different risk profile than one for an actively-growing ecosystem. Check the host platform’s activity, not the asset’s rarity, first.
The collector’s checklist
- Which platform does the asset work in — and is that platform shipping (engine upgrades, auctions, creator tools)?
- Is the asset’s utility inside a world, or purely cosmetic/speculative?
- Who operates the platform, and what happened to similar assets when other worlds cooled (the Decentraland cautionary tale: operational but thin usage)?
Sources
- CoinTelegraph — Metaverse NFT sales up 27% in August 2025
- TokTimes — The State of the Metaverse in 2026
- Bitrue — Metaverse Land Sales: Decentraland vs Sandbox
Related: Metaverse NFT sales in 2025 · Guides